Term
A large death benefit for a defined window — income, a mortgage, children still at home. Cheap on purpose. When the term ends, so does the coverage, unless you convert.
Shreveport & Bossier City · independent · since 2004
A 20-year term covers a window. Whole life stays. Infinite Banking is how some families use a designed whole life contract as a capital pool — recapture the interest, keep the death benefit, finance life on their terms. We pick the job first, then the company.
A large death benefit for a defined window — income, a mortgage, children still at home. Cheap on purpose. When the term ends, so does the coverage, unless you convert.
Permanent protection with a cash-value schedule that does not follow the market. Costs more. Has to be designed so it still works in year twenty, not just on page one of an illustration.
Same family of contract — different design, and a different use. You build cash value, borrow against it for things you’d otherwise finance, and recapitalize instead of paying a bank. The policy can keep growing while the loan is out. Loans are not free.
How Infinite Banking actually worksThe first question
Start with the job, not a premium. If you were gone tomorrow, what breaks — the house, the income, the kids still at home? The sketch on the right is a neighborhood, not a prescription. We use it so the first meeting isn’t a guess.
Most families in Shreveport & Bossier City who need a large number for a defined window start with term. Whole life and Infinite Banking are a different conversation, and we will say so if the budget cannot carry them.
Want the local checklist? Shreveport life insurance guide.
“Big shout out to The Squire Group and Mark Squire for helping me save almost $50 a month on my life insurance. The process was smooth, simple, and educational. I walked away with better coverage and stronger financial insight. As a father, protecting my son and my family isn’t optional.”
A sketch, not a recommendation
Families often start around ten to fifteen times pay. We add the mortgage and a modest amount per child so you can see the neighborhood.
Starting sketch
$1,750,000
$1,500,000 to replace income for 20 years · $150,000 mortgage · $100,000 set aside for 2 children. Ten times pay alone is $750,000. Term is usually the first conversation for a number this size.
This is not a quote and it is not “the right amount.” Debts, a stay-at-home spouse, a business, and what you already own all move it. We use it to see whether a conversation is even in the right zip code.
The Infinite Banking Concept
Term covers a window. Whole life stays, and it builds cash value on a schedule. Infinite Banking — the idea R. Nelson Nash wrote down in Becoming Your Own Banker — is a way of using a specially designed whole life policy as the place you store and deploy capital, so you stop renting money from someone else.
You are not opening a bank. The insurance company holds the contract. You are taking back the banking function: capitalize, lend, recapture the interest, do it again. The death benefit is still there for the people you love. That part matters as much as the strategy.
01
You fund a participating whole life contract designed for cash value — paid-up additions, not a skinny death-benefit page. That capital sits with a mutual carrier, growing on guarantees, with dividends extra when they’re paid.
02
When you would have financed a truck, equipment, a tuition bill, or a business move, you request a policy loan. The carrier lends against your cash value. No loan committee. No asking what it’s for.
03
Because it’s a loan against the policy — not a withdrawal — the cash value can keep compounding as if the money were still sitting there. That’s the uninterrupted compounding piece Nelson Nash was after.
04
You pay the loan back on your schedule, the way you would have paid a bank — except the interest stays inside a system you control. Next purchase, same pool. That’s why he called it infinite.
A truck, not a TED Talk
Say you were going to finance a truck. The dealer’s money is easy. The interest leaves your house and never comes back. In a capitalized Infinite Banking policy, you request a loan against cash value, pay cash for the truck, and recapitalize the policy the way you would have paid the bank.
The cash value can keep compounding while the loan is out. There is still a death benefit on the other side of it. That is the whole idea, without the Rockefeller mythology. Design is the whole game — two policies with a similar premium can behave nothing alike — and unmanaged loans accrue interest and can sink a contract. We show both columns before anyone applies.
Term · whole life · Infinite Banking
| Term | Whole life | Infinite Banking | |
|---|---|---|---|
| The job | A window of protection | Protection that is meant to last | Protection plus a capital pool you can use while you’re living |
| When it ends | When the term is over, unless you convert | It doesn’t, if you keep it in force | Same contract — the design is built to stay and to be used |
| While you’re alive | Pays if you die in the window | Cash value on a schedule; loans are a side door | You recapture financing you’d otherwise hand to a lender |
| Premium | Lower, on purpose | Higher, usually level | Higher, structured for early cash value and paid-up additions |
| Usual regret | Outliving the term | Paying for a need you didn’t have | Treating the loan provision like free money |
A sketch, not a quote
Use the ranges to decide whether a conversation is worth your time. Infinite Banking does not have an honest one-line premium — the design (base versus paid-up additions, early cash value, how soon you can use it) is the quote. That’s a meeting, not a widget.
Educational range
This is not a quote. Health, nicotine, occupation, riders, and the carrier all move the number. Use it to decide whether a conversation is worth your time.
$250,000 for 20 years
$26–$55/ month
Illustrative ranges only. Final pricing and eligibility depend on underwriting.
May be right if
Probably not if
What happens when you call
01
Tell us what you want protected. Bring a statement if you have one. You do not need the product name.
02
We compare carriers — including the policy you already own. If keeping it is the honest answer, that is the meeting.
03
Options in writing if something fits. Applying is optional. A no is a successful meeting.
Questions we hear in the office
Start with what would be financially broken if you were gone. Income for a window of years, a mortgage, children still at home. Ten to fifteen times pay is a common neighborhood — not a rule. Use the sketch on this page, then we size it to your household, including coverage you already have.
Ethos is one path for straightforward term. It is not a comparison across carriers, and it is not Infinite Banking. If you already have a quote from an advertisement, bring it — we’ll read the policy behind the pitch.
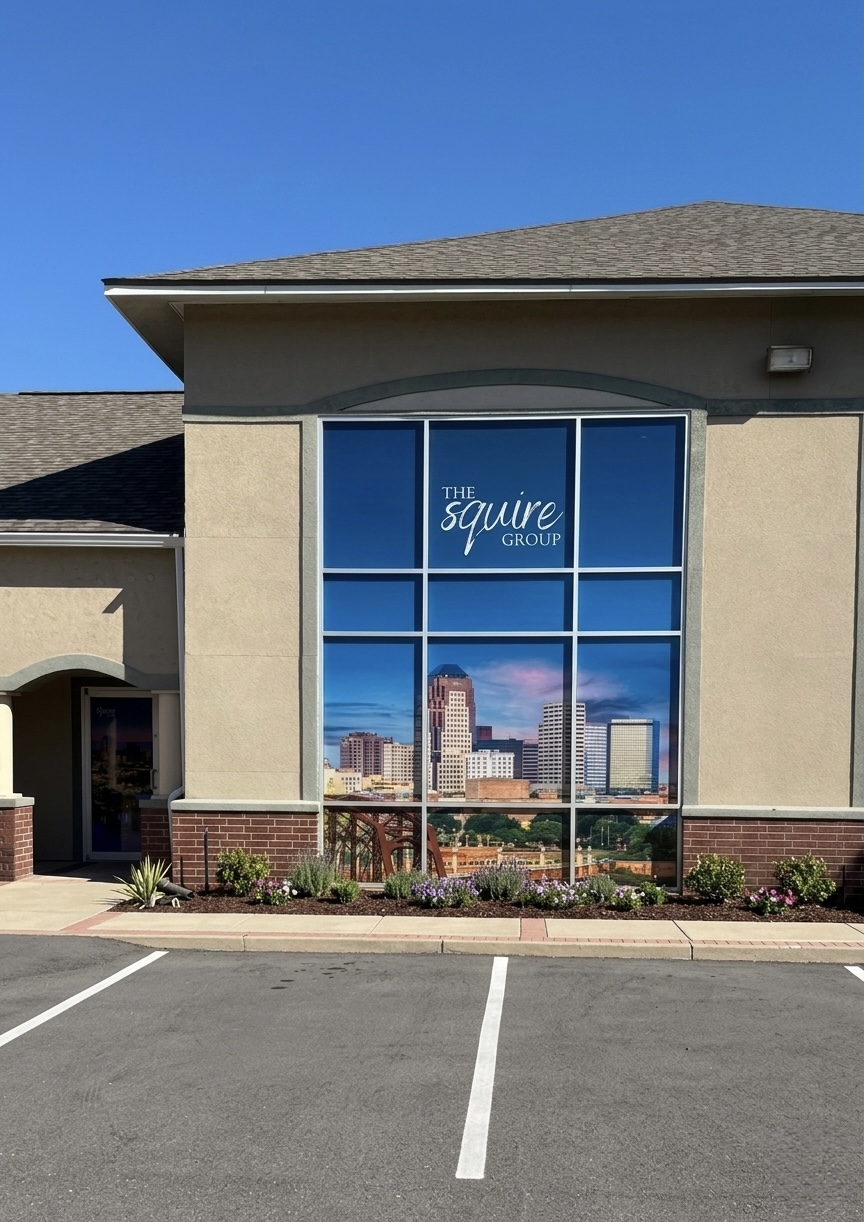
Come see us
Sit down. Get taught. Then decide.
8039 Line Avenue, Suite 1A
Shreveport, Louisiana 71106
318.900.8525 · mark@squiregrouplife.com
Twenty minutes
A conversation is not an application. If what you already have is doing the job, you will hear that.